News Articles
Public lecture gives a blue print for change in audit field
Management Sciences
CUT News
Sustainable Development (SDGs)
CUT hosted another successful public lecture on 22 May 2014. The series of lectures commenced in earnest in 2010 and gave rise to a number of great discourse opportunities for students, staff, and the community.
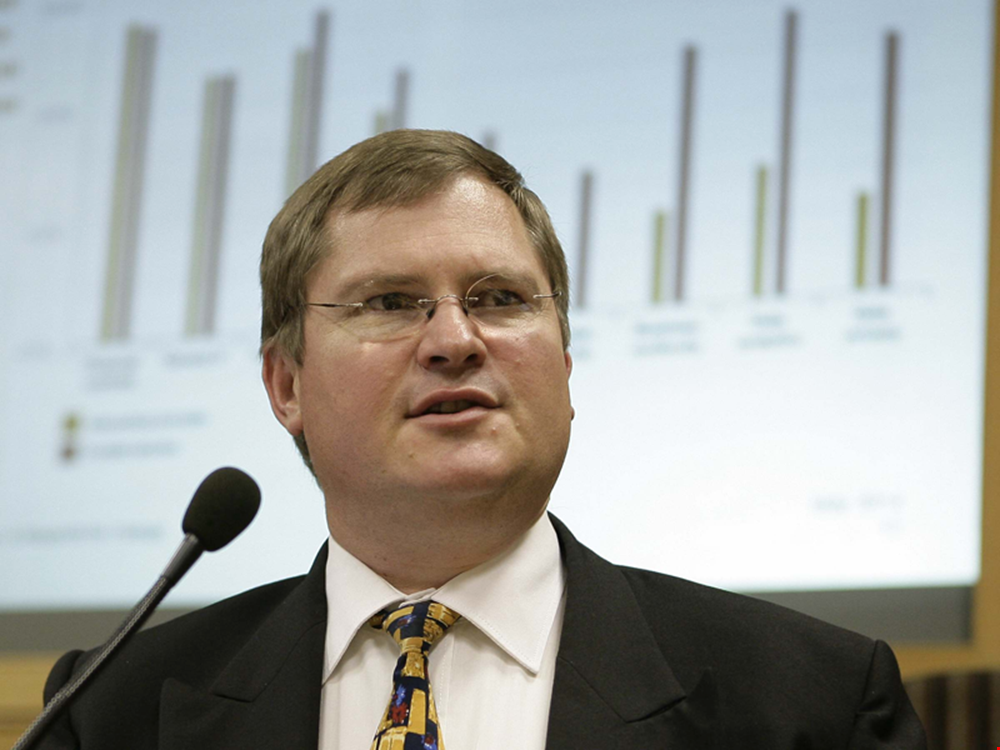
Mr Gerhard Geldenhuys, Director at PwC, and expert in the field of internal auditing was the guest speaker at the public lecture which was hosted in partnership with PwC. The lecture encompassed the state of internal audit profession globally. Twenty five industries in 37 countries were part of the internal audit profession survey conducted by PwC to determine what changes need to take place to keep the profession relevant. The overwhelming opinion of 1,700 executives participating in the 10th annual PwC State of the Internal Audit Profession Study is that internal audit needs to reach for new heights and contribute to the organisation in a more meaningful way. The research clearly indicates that internal audit must continue to evolve in its focus and significantly improve its performance—or risk losing relevance as other risk functions become more vital contributors to the organisation’s risk management.
According to Geldenhuys, the study identified three significant issues affecting many internal audit departments’ ability to deliver more value:
- Management and board members are not aligned on their perception of internal audit’s value and performance, and it appears as if board members may be settling for too little. A far greater percentage of board members than management believe internal audit contributes significant value.
- The foundational capabilities of internal audit may not be strong enough to deliver today’s work nor secure enough to build upon to generate greater value. As companies raise the bar on their own performance to contend with the ever-changing risk landscape and the greater regulatory and stakeholder expectations placed on them, they’re not raising the bar on internal audit at the same pace.
- Internal audit continues to struggle in maximising the impact of its contribution, particularly in areas outside of its more traditional focus. Stakeholders are least satisfied with internal audit’s contribution in emerging risk areas, such as large programme assessment, new product introductions, capital project management, and mergers and acquisitions.
Image
Mr Gerhard Geldenhuys, guest speaker at the public lecture.
News


